
Best Yearly Premium Auto Insurance in 2026 (Our Top 10 Picks)
Progressive, Allstate, and Nationwide have the best yearly premium auto insurance. Progressive's annual car insurance stands out for their expansive coverage options starting at $468/yr. Our guide helps you save with yearly premium car insurance as low as $264/yr. Find out which company has the best yearly auto insurance for you.
Read more
Find the Lowest Car Insurance Rates Today
Drivers have found rates as low as $42/month in the last few days!
Table of Contents
Table of Contents
Managing Editor
Laura Kuhl holds a Master’s Degree in Professional Writing from the University of North Carolina at Wilmington. Her career began in healthcare and wellness, creating lifestyle content for doctors, dentists, and other healthcare and holistic professionals. She curated news articles and insider interviews with investors and small business owners, leading to conversations with key players in the le...
Laura Kuhl
Licensed Auto Insurance Agent
Daniel Walker graduated with a BS in Administrative Management in 2005 and has run his family’s insurance agency, FCI Agency, for over 15 years (BBB A+). He is licensed as an insurance agent to write property and casualty insurance, including home, life, auto, umbrella, and dwelling fire insurance. He’s also been featured on sites like Reviews.com and Safeco. To ensure our content is accura...
Daniel Walker
Updated October 2026
Erie, Nationwide, and State Farm offer the best auto insurance with annual payments, with yearly rates starting at $624.
- Erie is best for longer rate stability between policy changes
- Nationwide is best for drivers interested in usage-based savings
- Annual payments may help avoid monthly installment fees
Erie’s Rate Lock helps keep premiums from changing at renewal unless you make certain policy changes. Check whether Erie offers a pay-in-full discount before choosing how to pay.
Nationwide’s SmartRide tracks driving habits like braking and acceleration, offering eligible drivers up to 40% in savings. You can also check whether paying your premium upfront reduces your total cost.
Our Top 10 Company Picks: Best Yearly Premium Auto Insurance
| Company | Rank | Multi-Vehicle Discount | A.M. Best | Best For | Jump to Pros/Cons |
|---|---|---|---|---|---|
 | #1 | 25% | A+ | Extensive Coverage | Progressive |
 | #2 | 14% | A+ | Membership Benefits | Allstate |
 | #3 | 16% | A+ | Competitive Rates | Nationwide |
 | #4 | 19% | A | Customizable Policies | Farmers |
 | #5 | 21% | A | Personalized Service | Liberty Mutual |
 | #6 | 15% | A | Innovative Coverage | AAA |
 | #7 | 17% | A++ | Member Discounts | Travelers |
 | #8 | 21% | A | Financial Stability | American Family |
 | #9 | 16% | A++ | Loyalty Rewards | USAA |
 | #10 | 14% | B | Military-Focused Benefits | State Farm |
State Farm’s Steer Clear rewards eligible drivers under 25 who complete its training program and meet safe-driving requirements.
Enter your ZIP code to compare yearly car insurance rates from providers in your area and find coverage that fits your budget and driving needs.
Six-Month vs. Yearly Auto Insurance Policies
Six-month and annual policies mainly differ in how often they renew. A yearly policy renews once a year, while a six-month policy renews twice.
With annual auto insurance, your rate is generally set for 12 months unless you make changes to your policy. A six-month policy renews sooner, so your rate can be adjusted earlier based on updated pricing factors.
When comparing semi-annual premium car insurance with yearly coverage, think about how often you want to renew. A six-month policy renews twice a year, while a 12-month policy only renews once.
Before choosing, look at what each option could cost over a full year. A lower six-month auto insurance rate to start may end up costing more if the price goes up at renewal.
Benefits of Choosing an Annual Auto Insurance Policy
A 12-month policy gives you more time between renewals. Your rate is generally set for the term unless you change your car, drivers, or coverage.
When comparing six-month and yearly options, look at what each one could cost over a full year instead of focusing only on the starting premium. Here are a few benefits of an annual policy:
- Easier Budgeting: Knowing your premium for the policy term can make planning your insurance costs simpler.
- Fewer Renewals: A 12-month policy renews once a year instead of twice.
- Later Rate Changes: New tickets or at-fault accidents may not affect your premium until your next renewal.
- Longer Rate Period: Your premium is generally set for 12 months unless you change your policy.
- Pay-in-Full Savings: Paying upfront may qualify you for a discount if your insurer offers one.
A yearly policy can make sense if you prefer fewer renewals and a longer period between rate reviews. Check the full annual cost, coverage, deductible, and available savings before choosing a policy term.
You can also check online auto insurance quotes to see how insurers price similar coverage before making your choice.
Free Insurance Comparison
Compare Quotes From Top Companies and Save
Comparing Annual Car Insurance Costs
Insurers consider your driving history, age, car, ZIP code, and coverage level when determining your annual premium. Because of these factors, the average cost of auto insurance may not reflect what you’ll actually pay for yearly insurance.
The same driver can get very different annual rates from insurers, even with similar coverage.
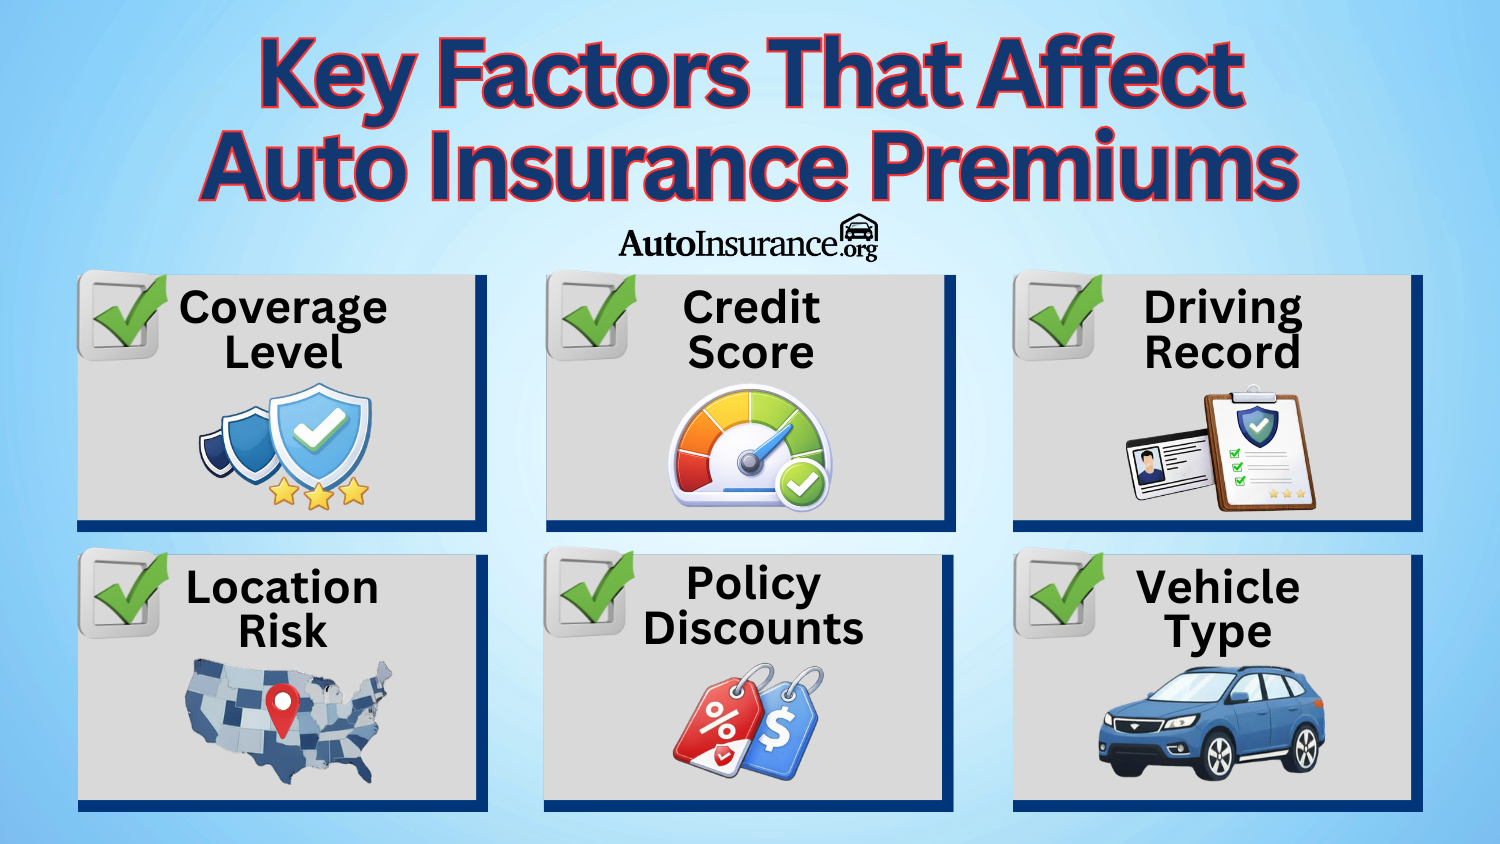
Choosing a higher deductible can lower your annual premium, but you’ll pay more out of pocket if you file a covered claim.
Bundling, safe driving, and low annual mileage may help you save without cutting back on your insurance protection.
I’d check what it costs to pay monthly versus upfront. Paying in full could save you from extra fees.Justin Wright Licensed Insurance Agent
Adding a driver, buying a new car, or moving to a different ZIP code can change your premium, so let your insurer know when something changes.
Before renewal, compare quotes to see if another insurer offers a lower rate or more ways to save.
Choosing Between Minimum and Full Coverage Insurance
The coverage you choose can make a big difference in what you pay for car insurance each year. Minimum coverage typically includes the liability insurance your state requires, so it usually costs less than full coverage.
Full coverage adds collision and comprehensive protection to help pay for damage to your car. You’ll pay more for these added protections, whether you pay your premium monthly or annually.
Yearly Premium Auto Insurance Rates by Coverage Level
| Insurance Company | Minimum Coverage | Full Coverage |
|---|---|---|
 | $384 | $1,032 |
 | $264 | $708 |
 | $528 | $1,404 |
 | $636 | $139 |
 | $816 | $2,088 |
 | $528 | $1,380 |
 | $468 | $1,260 |
 | $396 | $1,032 |
 | $444 | $1,188 |
 | $732 | $1,920 |
Have a newer car or an active auto loan? Your lender generally requires collision and comprehensive coverage until you pay off the loan.
Before paying annually, check what each coverage option costs and whether you can save by paying in full. Think about what you could afford to pay for repairs or a replacement after a claim, then shop around to see if you can get similar coverage for less.
How Location Affects Annual Car Insurance Costs
Where you live can make a difference in what you pay for car insurance. Rates vary by state based on factors such as insurance requirements, repair costs, and claim trends.
Use your state’s average as a reference when reviewing your options, but keep in mind that each insurer sets its own price.
Paying more than your state’s average is a good reason to review your protection level and deductible. Adjusting either one could change what you pay.
You can also check rates from other insurers to see if you could pay less for similar protection.
Learn More: Which states have the cheapest auto insurance rates?
How Your Credit Profile Affects Annual Car Insurance Rates
Your credit history can affect your car insurance costs. Before your policy renews, take a look at your financial profile to see if anything has changed.
If you’ve paid off debt or corrected an error on your credit report, comparing auto insurance companies could help you find a lower rate.
Insurers can weigh credit information differently when setting premiums. Compare insurance prices to see whether another company offers a lower annual rate for similar coverage.
California, Hawaii, Massachusetts, and Michigan limit how credit affects auto insurance rates. Your driver history and coverage choices can still affect what you pay.
Compare Annual Car Insurance Costs After a Violation
A ticket or at-fault accident can affect your premium differently depending on how an insurer evaluates driving violations.
Ask your insurer how long the incident will affect your rate. Speeding tickets and at-fault accidents can stay on your insurance record for several years, while a DUI may affect pricing longer.
Shopping for high-risk auto insurance? Check prices from other companies instead of relying only on your renewal rate.
Approved defensive driving courses may provide premium reductions based on state rules and insurer requirements.
If your rate goes up after a ticket or accident, ask if paying in full could save you money. It's worth checking before you renew.Melanie Musson Published Insurance Expert
Once a driving offense no longer affects your record, review your insurance options and ask your insurer for an updated rate.
Knowing when a surcharge ends can help you avoid paying it longer than your policy requires.
Related: Cheap Auto Insurance for a Bad Driving Record
How Driver Demographics Affect Annual Car Insurance Pricing
What you pay for car insurance can partly come down to your age and gender. Your driver history, location, vehicle, and protection level also factor into your rate.
Rates can change as you get older, but they don’t always move by the same amount each year. Gender can affect pricing, too, and the difference can vary by age and insurer.
Younger drivers may qualify for savings through approved driver training programs or good student discounts when they meet the insurer’s requirements.
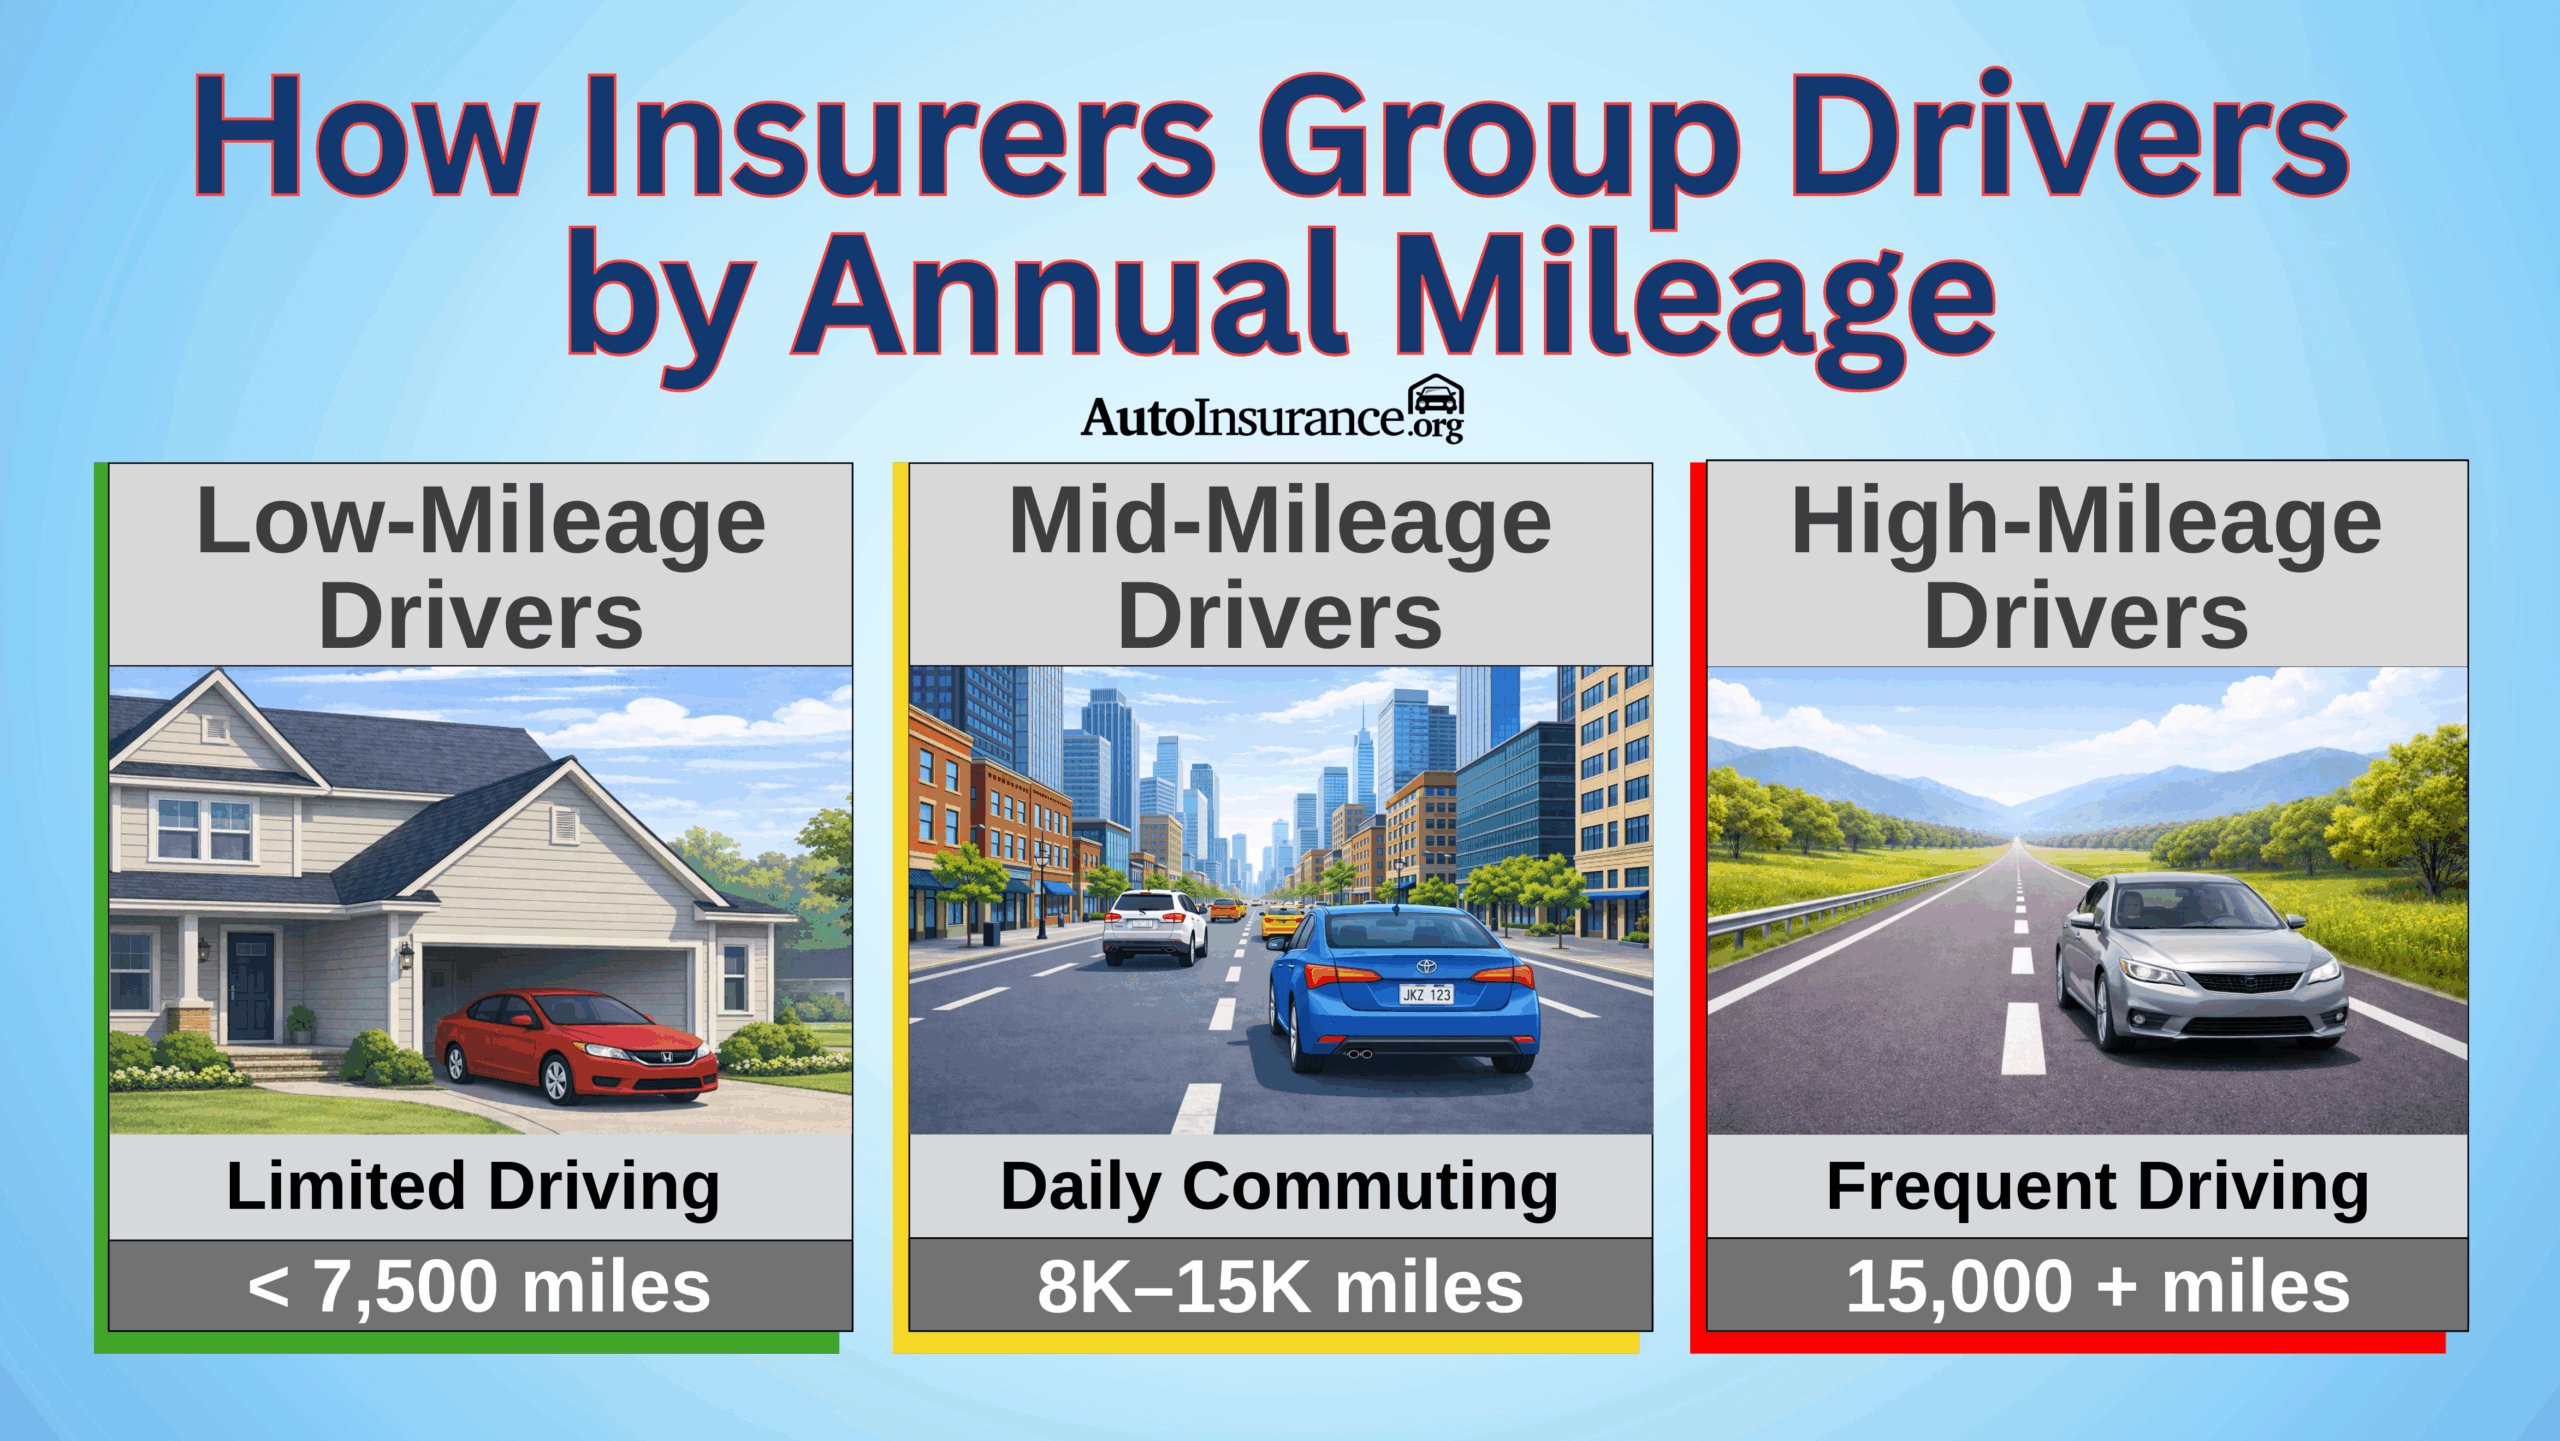
Retired or working from home? Keep your annual mileage updated so your insurer has an accurate idea of how much you drive. Some insurers use annual mileage ranges when setting rates, so even a small difference in how much you drive could affect your premium.
A birthday isn’t the only reason your premium can change. A claim, traffic violation, new driver, vehicle change, or different protection level can also affect your annual cost.
Understanding how auto insurance rates change with age can help you evaluate your renewal premium. If your current policy no longer fits your budget or needs, check your available coverage choices before your next renewal.
Further Reading: Auto Insurance Rates by Age
Yearly Premium Auto Insurance Coverage
Start with the car insurance coverage your state requires, then consider what else makes sense for your vehicle and budget.
The best car insurance companies have different policy options, so check what’s available before choosing your protection.
Common Car Insurance Protection
Your state decides how much liability coverage you need to carry. If you cause an accident, that coverage helps pay for the other person’s injuries or property damage.
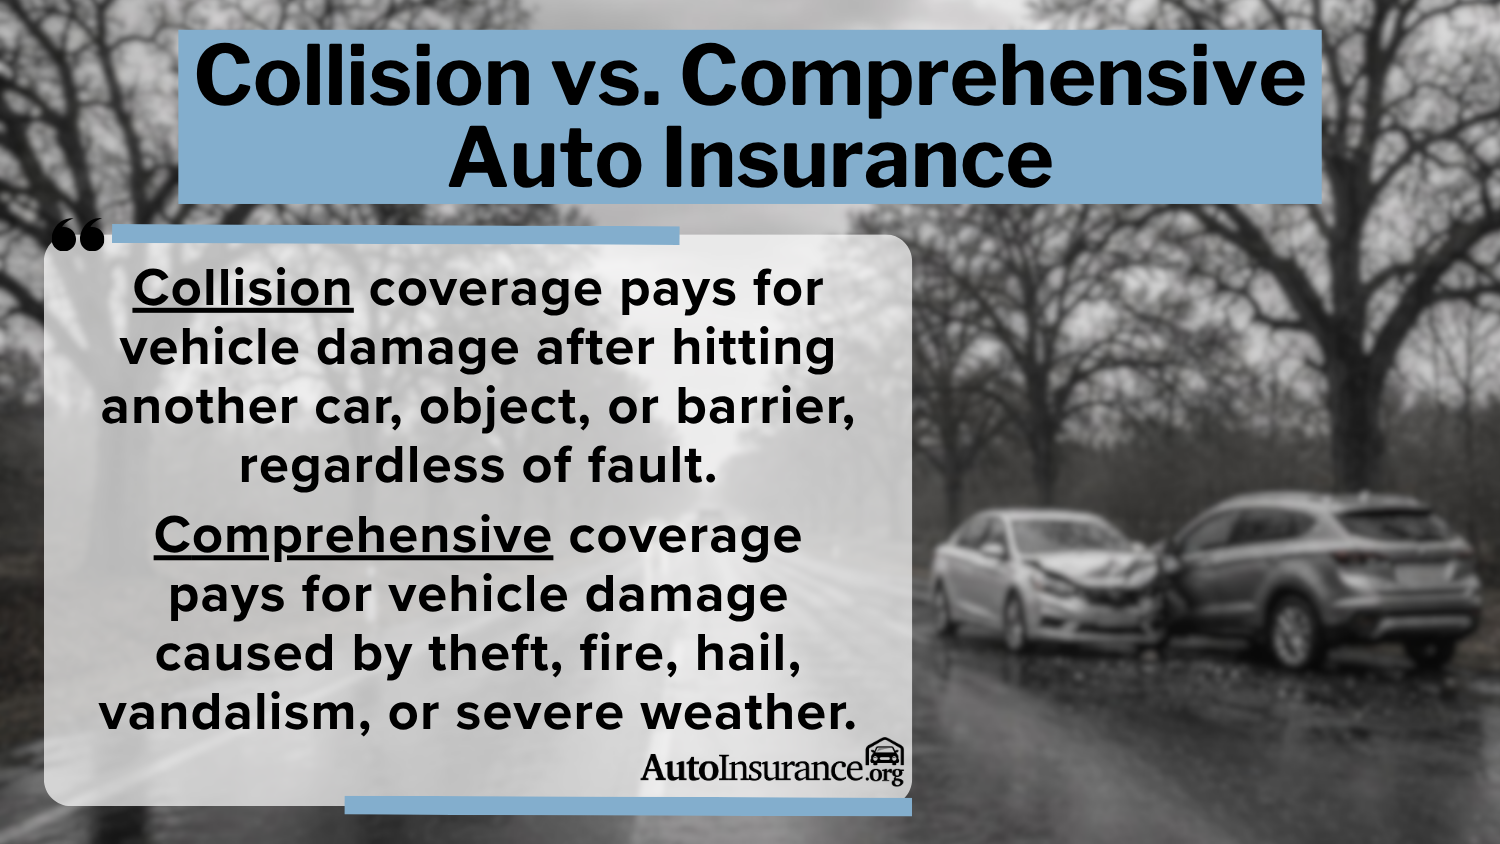
Collision and comprehensive coverage focus on your own car. Collision helps with repairs or replacement after a covered crash, while comprehensive covers things like theft, hail, fire, vandalism, and animal strikes.
Financing or leasing a vehicle can affect the protection you need. Check your agreement to see if collision, comprehensive, or gap insurance is required.
Once the loan or lease ends, take another look at your coverage to see if it still fits your vehicle and budget.
Optional Protection for Your Annual Policy
Need a temporary car while yours is being repaired after a covered claim? Rental reimbursement can help with the cost. Roadside assistance can also come in handy if you need a tow, jump-start, flat tire change, fuel delivery, or lockout service.
Added custom wheels, a premium sound system, or other permanent upgrades? Check whether your policy covers them or if you need additional protection.
When choosing additional coverage for your yearly auto insurance policy, consider:
- Gap Coverage: Helps cover what you still owe after a covered total loss.
- Medical Payments: MedPay helps pay eligible medical expenses for you and your passengers after an accident.
- Personal Injury Protection: Helps with eligible medical expenses and other covered costs after an accident.
- Uninsured and Underinsured Motorist: UM/UIM helps pay for your injuries or vehicle damage if the at-fault driver has little or no insurance.
Before adding optional protection, check what your current policy covers and what you could afford to pay after a claim.
If you’re paying annually, ask your insurer how adding coverage would affect your upfront cost.
Ways to Save on Annual Car Insurance Payments
Not every savings opportunity is available to every driver. Check which auto insurance discounts you qualify for before choosing a annual policy.
Bundling means buying another policy, such as home or renters insurance, from the same company. Low-mileage insurance discounts can also lower costs if you don’t drive many miles each year.
[table “13121” not found /]
Usage-based programs track driving habits such as speeding, hard braking, phone use, and quick acceleration. How you drive can affect the savings you receive, depending on the program.
Discounts aren’t the only way to lower your yearly premium. Your deductible, coverage choices, credit profile, and driving record can also affect what you pay.
- Check Rates Before Renewal: See how other insurers price similar coverage.
- Maintain a Clean Record: Avoiding tickets and at-fault accidents can help you avoid added costs at renewal.
- Raise Your Deductible: A higher deductible can lower your premium, but you’ll pay more after a covered claim.
- Recheck Your Protection: As your car ages, see if your current coverage still makes sense.
- Work on Your Credit: A stronger credit profile may help lower rates where credit-based insurance scoring is allowed.
Finding the best yearly premium auto insurance isn’t just about getting the biggest discount. Look at the annual cost, deductible, available savings, and what the policy covers before making a choice.
Before renewal, check personalized rates to see whether another insurer offers similar protection for less.
Find Out More: Best Companies for Bundling Home and Auto Insurance
Free Insurance Comparison
Compare Quotes From Top Companies and Save
How Yearly Auto Insurance Renewals Work
Your insurer reviews your rate when your policy renews. Your premium generally stays the same during your current term unless you make changes to your policy.
A new ticket, at-fault accident, claim, or loss of a discount could affect what you pay for your next term.
Insurers may also adjust renewal rates because of rising repair costs, claims expenses, or changes in local insurance pricing, even if your driving record hasn’t changed.
Paying your premium upfront doesn’t prevent renewal increases. Your insurer can still change your rate when your next policy term begins.
Auto Insurance Renewal
Your renewal notice shows the premium and coverage for your next policy term. Read through it before renewing to see whether anything has changed.
Check your insurance deductible, coverage limits, listed drivers, and vehicle details to make sure everything is accurate. Look at your discounts, too, since losing one could increase your premium.
I’d use renewal time to check whether your coverage still makes sense for your car. An older vehicle, for example, may not need every optional coverage.Dani Best Licensed Insurance Producer
If your renewal price is higher, ask your insurer what’s behind the increase. You can also compare quotes from other companies to see whether similar coverage costs less.
Planning to pay annually? Check whether paying upfront costs less than making installments before your new term starts.
Get More Details: When does my auto insurance renew?
What Underwriters Review Before Renewal
Your rate can change when a new policy term starts. Underwriters look at your driver and policy information to see what’s changed since your last term.
Those changes help determine what you’ll pay for the next one. Here are some of the details they may consider:
- Claims History: Your CLUE report and recent claims can affect your renewal premium.
- Discount Eligibility: Check whether you still qualify for multi-policy, multi-vehicle discounts, safe driver, paperless, or telematics savings.
- Driving Record: Includes new speeding tickets, at-fault accidents, DUIs, or other traffic violations.
- Household Drivers: Makes sure the drivers on your policy are listed correctly and accounts for any changes.
- Vehicle and Usage: Considers your car, annual mileage, commute, and how you use the vehicle when setting your rate.
Keep your driver, vehicle, and policy details current so your insurer has accurate information when setting your next premium. A clean driving record can also help you avoid surcharges tied to tickets or at-fault accidents.
If your price goes up, ask your insurer what changed and whether any savings are available. You can also check rates from other insurers before deciding whether to renew.
10 Best Auto Insurers With Annual Payments
Erie, Nationwide, and State Farm lead our rankings for yearly premium auto insurance, offering different benefits for rate stability, low mileage, and discounts.
Several major insurers offer yearly car insurance, but their market presence varies. The chart shows how five leading companies compare by market share.
Among these five insurers, State Farm has the largest share at 31%, followed by Progressive at 25%. Geico, Allstate, and USAA make up the rest of the group.
Check the cheapest car insurance companies if keeping costs down is a priority. To find the right policy, also consider claims service, available savings, coverage, and annual costs before choosing an insurer.
#1 – Erie: Top Overall Pick
Pros
- Rate Lock Protection: Erie’s Rate Lock keeps rates steady unless you make a qualifying policy change.
- Diminishing Deductible: Each claim-free year lowers your collision deductible by $100, up to $500.
- First Accident Forgiveness: Your first at-fault accident won’t trigger a surcharge after three years with Erie.
Cons
- Limited State Availability: Our Erie insurance review shows coverage is limited to 12 states and Washington, D.C.
- Agent-Based Service: Buying or updating coverage generally requires working with a local Erie agent.
#2 – Nationwide: Best for Low Mileage
Pros
- SmartMiles Pricing: SmartMiles combines a base rate with a mileage charge, so driving less can reduce costs.
- SmartRide Discount: Safe driving with SmartRide can save you up to 40%. Related: Nationwide Insurance Review
- Driving Feedback: SmartRide shows how you’re doing by tracking mileage, braking, acceleration, idle time, and nighttime driving.
Cons
- Seven-State Exclusion: SmartMiles isn’t available in Alaska, Hawaii, Louisiana, Michigan, North Carolina, New York, and Oklahoma.
- Variable Monthly Cost: Payments can change based on mileage recorded during the previous billing cycle.
#3 – State Farm: Best for Discount Variety
Pros
- Extensive Savings Programs: Drive Safe & Save, Steer Clear, Good Student, and multi-policy discounts provide several ways to save.
- Large Local Agent Network: State Farm has about 19,000 agents available to help with coverage changes and policy questions.
- Exceptional Financial Strength: State Farm holds an A+ AM Best Financial Strength Rating, indicating a strong ability to meet financial obligations.
Cons
- Discount Eligibility Requirements: Savings depend on factors such as driving history, location, and individual program requirements.
- State-Specific Coverage Options: Our State Farm insurance review shows coverage and discount availability can differ by state.
#4 – Auto-Owners: Best for Agent Support
Pros
- Personalized Agent Guidance: Independent agents help customers choose coverage based on their vehicles and insurance needs.
- Common Loss Deductible: When the same covered event damages your home and vehicle, you may only have to pay one deductible.
- Collision Coverage Advantage: The collision deductible may be waived when an accident involves another vehicle insured by Auto-Owners.
Cons
- Agent Purchase Required: Policies generally must be purchased and updated through an independent agent rather than entirely online.
- Limited Availability: Coverage is available in 26 states rather than nationwide. Explore More: Auto-Owners Insurance Review
#5 – American Family: Best for Loyalty Rewards
Pros
- Customer Loyalty Discounts: Long-term customers may qualify for savings based on how long they’ve stayed with American Family.
- KnowYourDrive Program: Safer driving recorded through KnowYourDrive may lead to additional savings.
- Generational Discount: Customers with parents who have American Family coverage may qualify for a generational discount.
Cons
- Limited State Availability: As noted in our American Family insurance review, policies are sold in 19 states.
- Program Availability Varies: Discounts and rewards depend on state regulations and individual eligibility.
#6 – Geico: Best for Online Savings
Pros
- Online Quote Savings: Qualifying customers may receive a discount when they get their Geico quote online.
- Military and Federal Discounts: Qualifying military members and federal employees may receive additional policy discounts.
- Mechanical Breakdown Insurance: Eligible newer vehicles can get protection for certain mechanical repairs beyond the manufacturer’s warranty.
Cons
- Primarily Digital Service: Policy management and claims support are largely handled online or by phone rather than through local offices.
- Claims Satisfaction: Geico received 697 out of 1,000 for claims satisfaction. See More: Geico Insurance Review
#7 – Allstate: Best for Bundle Savings
Pros
- Home and Auto Savings: Combining qualifying home and auto policies can provide savings of up to 25%.
- Deductible Rewards: Allstate cuts your collision deductible by $100 at signup and another $100 each accident-free year, up to $500, per the Allstate insurance review.
- Drivewise Savings: Completing at least 50 Drivewise trips can qualify participants for driving-based renewal savings.
Cons
- Bundle Savings Vary: Advertised savings aren’t available everywhere, and the discount amount depends on the state.
- Drivewise Trip Minimum: At least 50 recorded trips are required before a Drivewise score can qualify for savings.
#8 – Travelers: Best for Driver Tracking
Pros
- 90-Day Tracking: IntelliDrive tracks your driving for 90 days, so you know exactly how long the program monitors your habits.
- Trip Corrections: You have 10 days to fix trips the app incorrectly records as yours.
- Driving Feedback: You can review your recorded driving habits while using IntelliDrive. Discover More: Travelers Insurance Review
Cons
- Rate Can Increase: Riskier driving with IntelliDrive 365 can raise your rate by up to 45% where allowed.
- 500-Mile Minimum: You need to record at least 500 miles within 90 days to receive a score.
#9 – Farmers: Best for Policy Flexibility
Pros
- Multiple Coverage Add-Ons: Farmers offers OEM parts, rideshare, glass, residual debt, and other optional coverages.
- Residual Debt Protection: Farmers can pay up to 25% above your vehicle’s actual cash value toward the remaining balance, as explained in our Farmers insurance review.
- OEM Parts Coverage: Farmers may pay for original manufacturer parts if your qualifying vehicle is up to 10 years old.
Cons
- Accident Forgiveness Limit: Farmers only forgives one at-fault accident every three years for qualifying customers.
- Coverage Varies by State: Some coverage options aren’t available everywhere, so what you can add depends on where you live.
#10 – Progressive: Best for Risky Drivers
Pros
- SR-22 Support: Progressive can file an SR-22 when required after certain serious driving violations.
- Continuous Coverage Discount: Your previous insurance history may qualify you for savings when switching to Progressive.
- Accident Forgiveness: Qualifying claims of $500 or less won’t result in a rate increase under Small Accident Forgiveness.
Cons
- SR-22 Filing Cost: You’ll generally pay an additional fee when Progressive files an SR-22 for you. Read More: Progressive Insurance Review
- Limited Local Agents: Most Progressive customers handle their coverage online or by phone rather than with a local agent.
Getting the Best Auto Insurance With Annual Payments
Finding the best auto insurance with annual payments also means knowing what happens to your money if your plans change. Before paying upfront, ask your insurer how cancellations, refunds, and midterm policy changes work.
Planning to sell your car or switch insurers? Ask whether you’ll get a refund for the coverage you haven’t used.
This is worth knowing when shopping for affordable yearly auto insurance, especially if you’re unsure whether you’ll keep the same policy all year.
You can also review the types of auto insurance available if your needs change during the policy period. Ask how adding or removing coverage would affect a premium you’ve already paid.
Don't wait until after an accident to understand your policy. In particular, take a few minutes to review what's covered before renewing.Jeff Root Licensed Insurance Agent
The best car insurance company should clearly explain how it handles policy changes after you’ve paid in full. Find out whether you’ll owe an additional amount or receive a refund if your premium changes.
Compare yearly auto insurance quotes from top providers in your area and choose the policy that best fits your budget and driving needs.
Frequently Asked Questions
What is annual auto insurance?
Annual auto insurance refers to a type of vehicle insurance policy that provides coverage for a period of one year. It is a contract between an individual and an insurance company, where the individual pays a premium in exchange for financial protection in case of accidents, theft, or damage to their vehicle.
What does annual auto insurance typically cover?
Annual auto insurance policies generally provide coverage for the following:
- Liability coverage: Pays for damages caused to other people or their property in an accident where you are at fault.
- Collision coverage: Covers repairs or replacement of your vehicle if it is damaged in a collision with another vehicle or object.
- Comprehensive coverage: Protects your vehicle against non-collision events such as theft, vandalism, fire, or natural disasters.
- Personal injury protection: Covers medical expenses and lost wages for you and your passengers in case of injury during an accident.
- Uninsured/underinsured motorist coverage: Pays for damages if you are involved in an accident with a driver who has no insurance or insufficient coverage.
What is the annual premium insurance rate for car insurance?
The rates for car insurance can vary widely. Annual insurance costs depend on several factors, including your age, location, driving record, the car you drive, and the coverage you choose. It’s always best to get multiple auto insurance quotes to find the best rate for your specific situation.
What are the advantages of annual auto insurance?
Some benefits of annual auto insurance include:
- Continuous coverage: With an annual policy, you have consistent protection throughout the year, reducing the risk of driving uninsured.
- Potential savings: Insurers often offer discounts for purchasing an annual policy, which can lead to cost savings compared to shorter-term policies.
- Convenience: You don’t need to worry about renewing your policy frequently, as it remains in effect for the entire year.
- Flexibility: Annual policies may provide options for customization, allowing you to tailor coverage to your specific needs.
Are there any disadvantages to annual auto insurance?
Some potential drawbacks of annual auto insurance are:
- Higher upfront costs: Compared to shorter-term policies, annual insurance requires a larger upfront premium payment.
- Limited flexibility: Once you commit to an annual policy, it may be challenging to make changes or switch to a different provider before the term expires.
- Overpaying for unused coverage: If you sell your vehicle or no longer need the insurance during the policy term, you may end up paying for coverage you don’t use.
- Inflexible cancellation terms: Cancelling an annual policy before its expiration date may result in fees or penalties, depending on the insurer.
Can I switch insurers during the term of my annual auto insurance policy?
While it is possible to switch insurers during the term of your annual auto insurance policy, there may be limitations or penalties involved. It is essential to review the terms and conditions of your policy or consult with your insurance provider to understand the specific rules regarding mid-term cancellations or switching providers (Read more: Managing Your Auto Insurance Policy).
How can I find the best annual auto insurance policy for my needs?
To find the best annual auto insurance policy, consider the following steps:
- Evaluate your coverage needs: Determine the level of coverage required for your vehicle based on factors like its value, usage, and personal circumstances.
- Shop around: Obtain quotes from multiple insurance companies to compare prices, coverage options, and customer reviews.
- Assess discounts: Inquire about available discounts such as safe driver discounts, multi-policy discounts, or discounts for safety features in your vehicle.
- Review deductibles: Consider the deductible amount you are comfortable with, as it affects your out-of-pocket expenses in case of a claim.
- Read policy terms: Carefully review the terms, conditions, and exclusions of the policy before making.
Which car insurance has the highest customer satisfaction?
Based on various rankings and reviews, companies like Amica Mutual, USAA, and State Farm are often ranked highly for customer satisfaction. Reputable resources for customer satisfaction ratings include J.D. Power, A.M. Best, and Consumer Reports.
Is it cheaper to pay yearly for car insurance?
Typically, yearly auto insurance policies are going to be cheaper than other plans in the long run. Short-term and upfront costs are higher. A good way to save money by bundling insurance policies
Why is annual premium cheaper than monthly?
Annual premium car insurance is often cheaper than monthly payments for several reasons. Some reasons are lower administrative costs, reduced risk of non-payment, potential annual premium discounts, and less interest charges.
Who has the lowest premium rate for vehicle insurance?
Can I negotiate insurance premiums?
Related Articles
-
Oct 2024

Best Auto Insurance for Regular Maintenance in 2026 (10 Expert Favorites)
-
Dec 2024
Should I pay my auto insurance in full?
-
Dec 2024
Auto Insurance Binder Defined (2026 Guide)
-
Oct 2024
Best Windshield Replacement Coverage in Minnesota (Top 10 Companies in 2026 )
-
Nov 2024
Rental Car Reimbursement Coverage in 2026 (Insurance Guide)
-
Oct 2024
Best Windshield Replacement Coverage in Virginia (Top 10 Companies for 2026)

Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.